
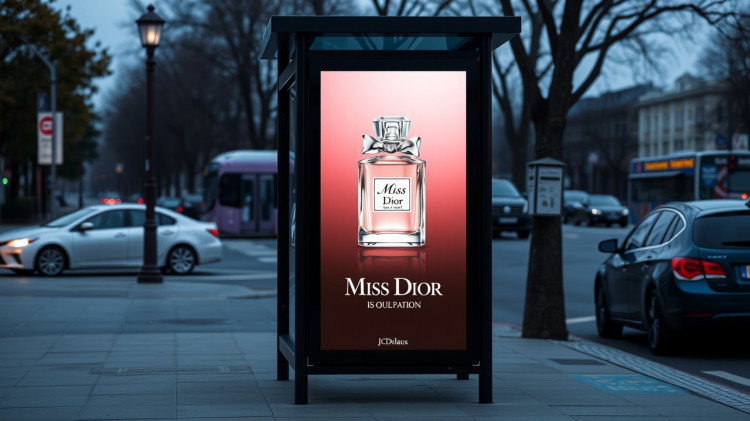
JCDecaux, the French advertising company, may not look like a typical AI investment. Still, its worldwide audience gives investors an unusual way to gain exposure. Is the stock worth buying?
?
JCDecaux (Paris: DEC) has emerged as an unlikely beneficiary of the global AI boom. It owns thousands of billboards and other advertising assets around the world, so few investors would immediately treat it as an AI stock. Yet its extensive physical footprint is gaining value as advertisers redirect spending, and investors have started to recognize that opportunity. The shares are up more than 70% this year alone.
Why JCDecaux's advertising strategy works
JCDecaux operates in the out-of-home (OOH) advertising market. As I noted in a recent feature, it is one of the few traditional advertising channels to have attracted growing advertiser demand over the past decade. WPP, one of the world's leading advertising companies, expects global OOH advertising revenue to rise 5% to £57.5 billion in 2026, followed by another 5.3% increase in 2027. Its forecast puts the market at £73.7 billion by 2031. WPP describes that trajectory as a "structural anomaly": radio, TV and print are taking smaller shares of global advertising spending, while OOH continues to hold its ground.
Digital platforms claim the biggest portion of the global advertising market, which generates £720 billion a year. Facebook and Google alone make up half of that spending, largely by directing users to websites where they can purchase products or services. Now AI platforms such as ChatGPT and Gemini are entering the same space, placing ads inside their responses; that market could surpass £100 billion by 2031, compared with just £5 billion today.
Advertising has always lost some of its audience to this kind of "leakage," but never on this scale. OOH closes much of that gap. An advertiser can choose a fixed site - Bank Underground station in the City of London, for example - and reach tens of thousands of people passing through each day. Digital ads can target a defined audience, yet there is no certainty that the person or device actually sits where the data places it. Physical sites are harder to misrepresent: stations, airports, and shopping centres do not move, and those are where the most valuable OOH billboards are usually found. Stadiums rank highly too.
OOH is not replacing digital advertising; it works alongside it. Its main job is to keep a brand visible and build recognition, which may make someone more likely to click a similar ad when it later appears online. As Berenberg analysts put it, OOH meets the "critical need for brand differentiation as AI rapidly commoditises content."
JCDecaux's family success story
In 1964, Jean-Claude Decaux created a new kind of outdoor advertising: "street furniture." His first bus shelters, installed in Lyon, France, were paid for through advertising. The idea crossed Europe two years later, and JCDecaux's business grew with the wider advertising market. Working with local governments, agencies, clients, and designers such as Norman Foster, the company has since developed street furniture and OOH advertising sites that suit their surroundings while putting otherwise unused space to work.
The founding Decaux family remains the majority owner, with a 66% stake held through JCDecaux Holding SAS. JCDecaux accounts for 12% of the global OOH market, making it the largest individual player. France remains its biggest market, generating 17% of revenue, while the UK contributes 11% and the US 8%. Another 30% comes from the rest of Europe, 21% from Asia-Pacific, and 14% from other parts of the world. Street furniture brings in just over half of group sales and produces 66% of earnings before interest, tax, depreciation and amortisation (Ebitda).
Should you invest in JCDecaux?
JCDecaux (Paris: DEC)
Running OOH assets requires relatively little capital or other resources. The company has kept Ebitda margins close to 20% in recent years, and Berenberg expects them to reach 22.2% by 2028. Debt stands at a manageable 1.1x Ebitda. Free cash flow is forecast at 336 million in 2025 and 354 million by 2028, giving analysts confidence that the company can clear its debt within three years.
That seems unlikely. The group is pursuing deals across several markets, typically worth around 100 million, or about 50% of annual free cash flow after dividends. Even if none materialize, Berenberg expects revenue to track the market over the coming years, while adjusted Ebitda grows faster - by 6%-9% - as margins widen.
Even after rising 70% this year, the shares still look reasonably priced: 17.1 times forward earnings, with a 6.6% free-cash-flow yield. That valuation seems to ignore both the company's growth prospects and the possibility of bolt-on acquisitions. Based on Berenberg's 2028 estimates, JCDecaux trades at 14.4 times earnings and offers a 7.2% free-cash-flow yield. Investors also receive a 3% dividend yield.
JCDecaux has a strong balance sheet and generates free cash flow, while its position in a market exposed to AI risk appears to be holding up against digital competition.




Leave a comment on: How JCDecaux quietly emerged as an unlikely AI-boom winner