
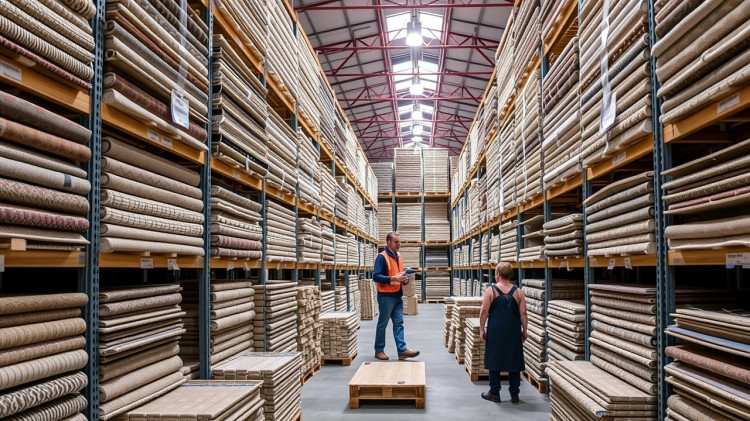
Similarly, Group acted swiftly to take advantage of a competitor's setback
The future appears promising, should you purchase?
Tony Brewer's role as CEO of Likewise Group (Aim: LIKE) is the culmination of a protracted business rivalry. Brewer made Headlam, a distributor of flooring in the UK, the industry leader. However, on September 1st, it went into administration, and he is currently in charge of the business that replaced it.
At the age of 17, Brewer began working in the carpet industry at Midlands Carpet Distributors (MCD) in 1977. There, he gained experience under Graham Waldron, the company's founder. Brewer and Waldron purchased a 22 percent share in the publicly traded company Headlam in 1991. At the time, Waldron was the CEO. The company was transformed into a focused flooring distributor with the goal of consolidating the UK wholesale floor-coverings market by eliminating its previous footwear and textile divisions.
Hundreds of small, family-run businesses made up the trade at the time. The majority lacked purchasing power with continental mills, operated ineffective local delivery routes, and carried modest inventory. In order to maintain regional trading names and centralize supplier negotiations, Brewer and Waldron saw an opportunity and started purchasing these operators.
Headlam emerged as one of the top-performing stocks in the London market between 1991 and the 2008 financial crisis, producing operating margins close to 8% and returns on capital employed comfortably above 20%. Numerous private distributors were driven to their knees by the precipitous decline in flooring installations when the crisis stopped UK housing transactions. After absorbing the shock and taking over the displaced accounts, Headlam emerged with about 30% of the domestic wholesale market.
Both employees and investors held Brewer in high regard. In 2016, the board took action. A boardroom breakup caused by disagreements over succession and operational strategy resulted in Brewer leaving the company he had spent 25 years building.
Brewer was persuaded that Headlam was weak after two years of banishment. With a vast network of regional properties and central administrative overheads, the market leader had become indebted and bureaucratic under the new management. In order to raise development funds, Brewer and real estate investor Paul Bassi founded Likewise Group in 2018 and floated the company on Aim. The goal was straightforward: create a cutting-edge distributor that could duplicate Headlam's initial service model without carrying over its structural deadweight.
Logistics and connections are key to the distribution of flooring at wholesale prices. Self-employed carpet installers, independent flooring retailers, and local contractors lack the funds and warehouse space necessary to maintain substantial inventories. The distributor supplies the necessary delivery infrastructure, carries the inventory, and offers trade credit.
Just as important are relationships. Instead of purchasing from a corporate brand, independent retailers and trade fitters typically purchase from sales representatives they trust to handle delivery issues and secure stock allocations. 120 to 140 commercial accounts are usually handled by a competent sales representative. Brewer heavily recruited from Headlam's commercial team by leveraging his position in the industry. Numerous salespeople, regional managers, and senior logistics directors relocated to Likewise over a number of years. Many of their local trade clients relocated with them.
As a result, Headlam experienced a detrimental drop in volume. Falling volumes can quickly reduce profits and result in painful losses in wholesale distribution, where operating margins rarely surpass mid-single digits due to high fixed costs in depot leases and central overheads. Headlam's overheads overtook operating cash flow as sales declined, converting steady profits into trading losses and increasing the burden on its debt facility until liquidity ran out. It won't be easy to seize the rewards of Headlam's demise. The ineffective retailers of the 1990s no longer dominate the UK wholesale market. The independent distributors that are still in operation are well-run, disciplined companies with spotless balance sheets and devoted local clientele. Every square yard of volume that is displaced will be contested.
Group has ample space to expand as well.
For many years, Group has also been receiving shares from Headlam. Its sales operation is based on many of the individuals who are familiar with Headlam's clients, and its national network is more recent but smaller. Therefore, a process that was already in progress is accelerated when Headlam falls into administration.
Before it can handle much more trade, the company must invest in warehouses, equipment, and inventory. This explains why Likewise Group raised an additional £32.5 million in equity in July. The money raised is being used by management to finance the freehold logistics facilities required to manage the increased trade.
Similarly, Group now has a sizable amount of spare capacity. The additional revenue should come with minimal additional distribution costs as displaced contractor orders and stranded trade accounts enter its national network. Therefore, shifting from current revenue run-rates to its 300 million capacity ceiling could increase operating margins from the current 2.5 percent to 5 percent, or 6 percent if the UK housing cycle improves.
That throughput produces an annual operating profit of between £15 million and £18 million when operating at full capacity. The shares trade on less than seven times mature operating profit compared to an enterprise value of approximately £100 million. Numerous inexpensive small-cap stocks languish in the Aim market in the absence of a catalyst. has one, too. Ironically, the man who constructed Headlam is now in the best position to take up its legacy.
Group likewise (Aim: LIKE).



Leave a comment on: Likewise Group: a low-cost small-cap with enormous potential